Milan, 24 Sept. (LaPresse) – The risks to the inflation outlook “are tilted to the upside, mainly due to the conflict in the Middle East and developments in Russia’s unjustified war against Ukraine. The energy shock could intensify further, and the effects on other prices and wages could prove more pronounced than currently expected. In particular, gas prices could rise in the event of further supply disruptions or an unusually harsh winter coinciding with low stock levels.” The ECB notes this in its Economic Bulletin. Furthermore, persistently high energy prices “would make a generalised rise in inflation more likely through indirect and second-round effects. New trade tensions could lead to greater fragmentation of global supply chains, reduce the supply of critical raw materials and exacerbate production capacity constraints in the euro area economy”. In addition, “extreme weather events, potentially exacerbated by the intensification of ‘El Niño’-related conditions, and, more generally, the unfolding climate and environmental crisis, could lead to higher-than-expected increases in food prices”. Conversely, inflation could turn out to be lower “if the current geopolitical conflicts were to be resolved in a lasting manner, or if the indirect or second-round effects stemming from the recent energy price shock proved to be less pronounced than anticipated. More volatile and risk-averse financial markets could weigh on demand and, in turn, reduce inflation”.
ECB: ‘Inflation risks are tilted to the upside, with energy price rises weighing heavily’
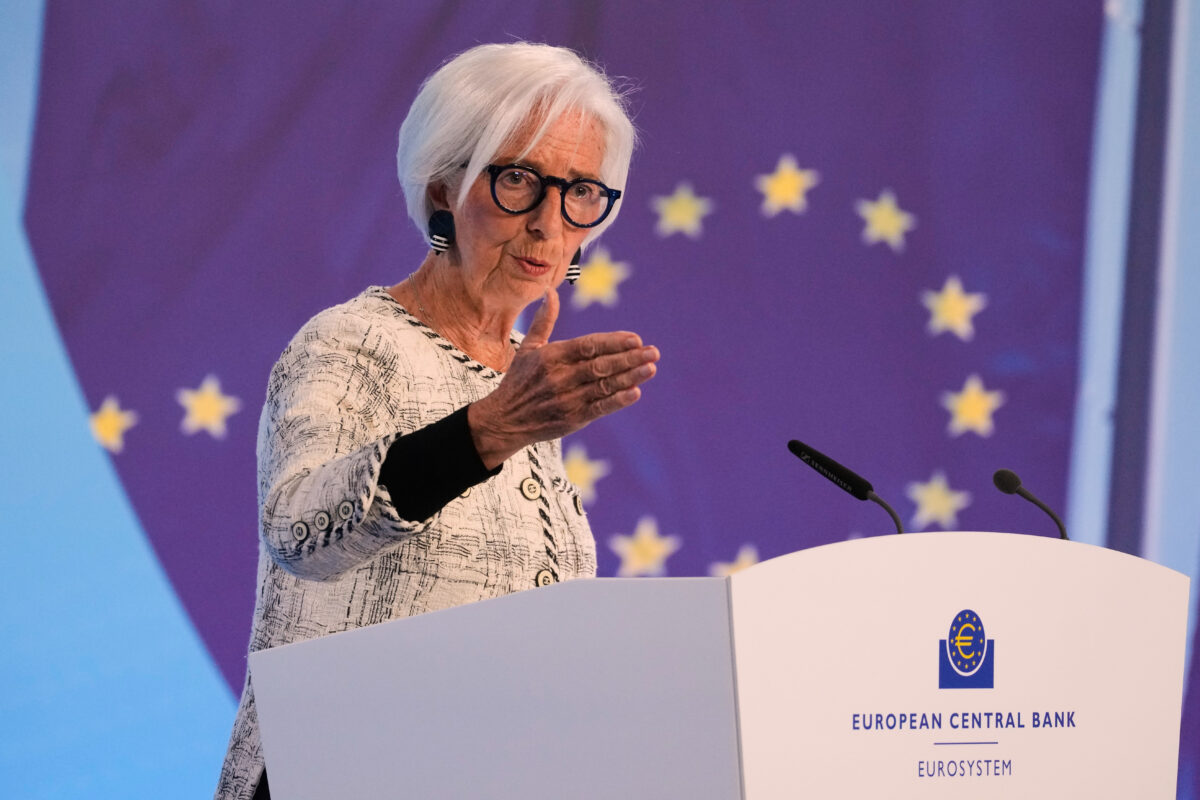
Milan, 24 Sept. (LaPresse) – The risks to the inflation outlook “are tilted to the upside, mainly due to the conflict in the Middle East and developments in Russia’s unjustified war against Ukraine. The energy shock could intensify further, and the effects on other prices and wages could prove more pronounced than currently expected. In particular, gas prices could rise in the event of further supply disruptions or an unusually harsh winter coinciding with low stock levels.” The ECB notes this in its Economic Bulletin. Furthermore, persistently high energy prices “would make a generalised rise in inflation more likely through indirect and second-round effects. New trade tensions could lead to greater fragmentation of global supply chains, reduce the supply of critical raw materials and exacerbate production capacity constraints in the euro area economy”. In addition, “extreme weather events, potentially exacerbated by the intensification of ‘El Niño’-related conditions, and, more generally, the unfolding climate and environmental crisis, could lead to higher-than-expected increases in food prices”. Conversely, inflation could turn out to be lower “if the current geopolitical conflicts were to be resolved in a lasting manner, or if the indirect or second-round effects stemming from the recent energy price shock proved to be less pronounced than anticipated. More volatile and risk-averse financial markets could weigh on demand and, in turn, reduce inflation”.